Modern online payday loans replace storefront queues and physical paperwork with encrypted digital underwriting and Automated Clearing House (ACH) direct deposit. When an unexpected automotive repair, urgent dental procedure, or utility disconnection notice arrives before your scheduled paycheck, understanding how web-based cash advance portals verify income and settle funds helps you borrow safely and transparently.
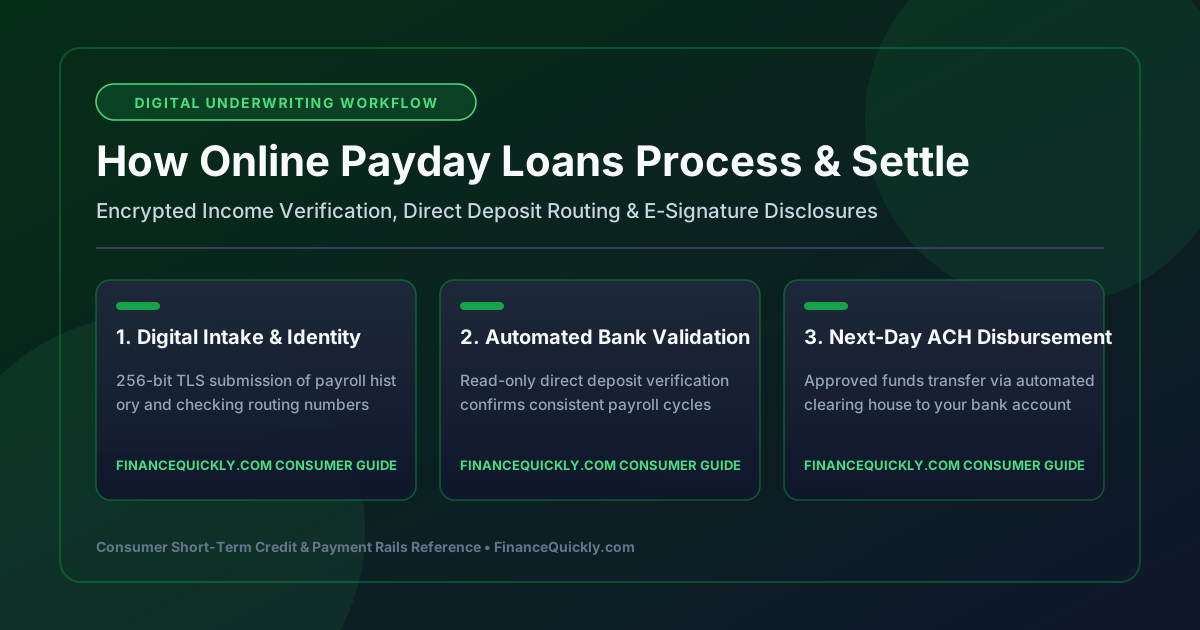
How Web-Based Cash Advance Underwriting Operates
Unlike commercial bank personal loans that require multi-week underwriting reviews and prime FICO credit scores, state-licensed online short-term lenders evaluate your real-time payroll cash flow. When you submit an application on FinanceQuickly.com, three verification layers run in parallel:
- 256-Bit TLS Data Intake: Your identity, employment schedule, and nine-digit ABA bank routing and checking account numbers are transmitted over encrypted transport channels.
- Read-Only Payroll Deposit Verification: Automated bank verification confirms that your checking account receives consistent electronic direct deposits from a verified employer or benefit administrator.
- Specialty Credit Bureau Screening: Rather than triggering a hard pull on Equifax, Experian, or TransUnion, participating originators check specialty subprime reporting bureaus such as Teletrack, Clarity Services, or DataX to confirm you have no active unpaid short-term defaults.
Comparing Digital Payday Advances Against Conventional Bank Credit
| Underwriting Dimension | Online Payday Advance | Traditional Bank Personal Loan |
|---|---|---|
| Primary Approval Metric | Verified recurring payroll direct deposit ($800+/mo) | FICO 8 credit score (660+) & low debt-to-income ratio |
| Application & Decision Speed | 5-minute digital form; automated decision in minutes | Multi-page application; 3 to 7 business days review |
| Disbursement Mechanism | Next-business-morning ACH credit (or same-day batch) | Branch closing or multi-day wire/ACH transfer |
| Repayment Structure | Single-cycle ACH debit on your next scheduled pay date | 12 to 60 monthly amortizing installment payments |
Reviewing Mandatory Truth in Lending Disclosures Before E-Signing
Before applying your electronic signature under the federal E-SIGN Act, always inspect the Truth in Lending Act (TILA) disclosure box presented by your matched lender. Confirm the exact dollar finance charge per $100 borrowed, the equivalent Annual Percentage Rate (APR), and the exact calendar date on which the combined principal and fee will be debited from your checking account.